ExamineAI
First page of ZIMSEC O-Level Principles of Accounts Paper 1 June 2013 Question Paper

ZIMSEC O-Level Principles of Accounts Paper 1 June 2013 Question Paper

Download and practise with this ZIMSEC O-Level Principles of Accounts Paper 1 June 2013 question paper. Useful for exam revision, past paper practice, and preparation in Zimbabwe.

A free account is needed to download. Sign in or create one

Exam board
ZIMSEC
Subject
Principles of Accounts
Level
O-Level
Document
Question Paper
Paper
Paper 1
Paper code
9197/1
Session
June
Year
2013
File
PDF, 494 KB

About this question paper

This is the ZIMSEC O-Level Principles of Accounts question paper for Paper 1 from June 2013. Use it for exam practice under timed conditions. The paper code is 9197/1.

More Principles of Accounts O-Level 2013 papers

Other years: Principles of Accounts O-Level

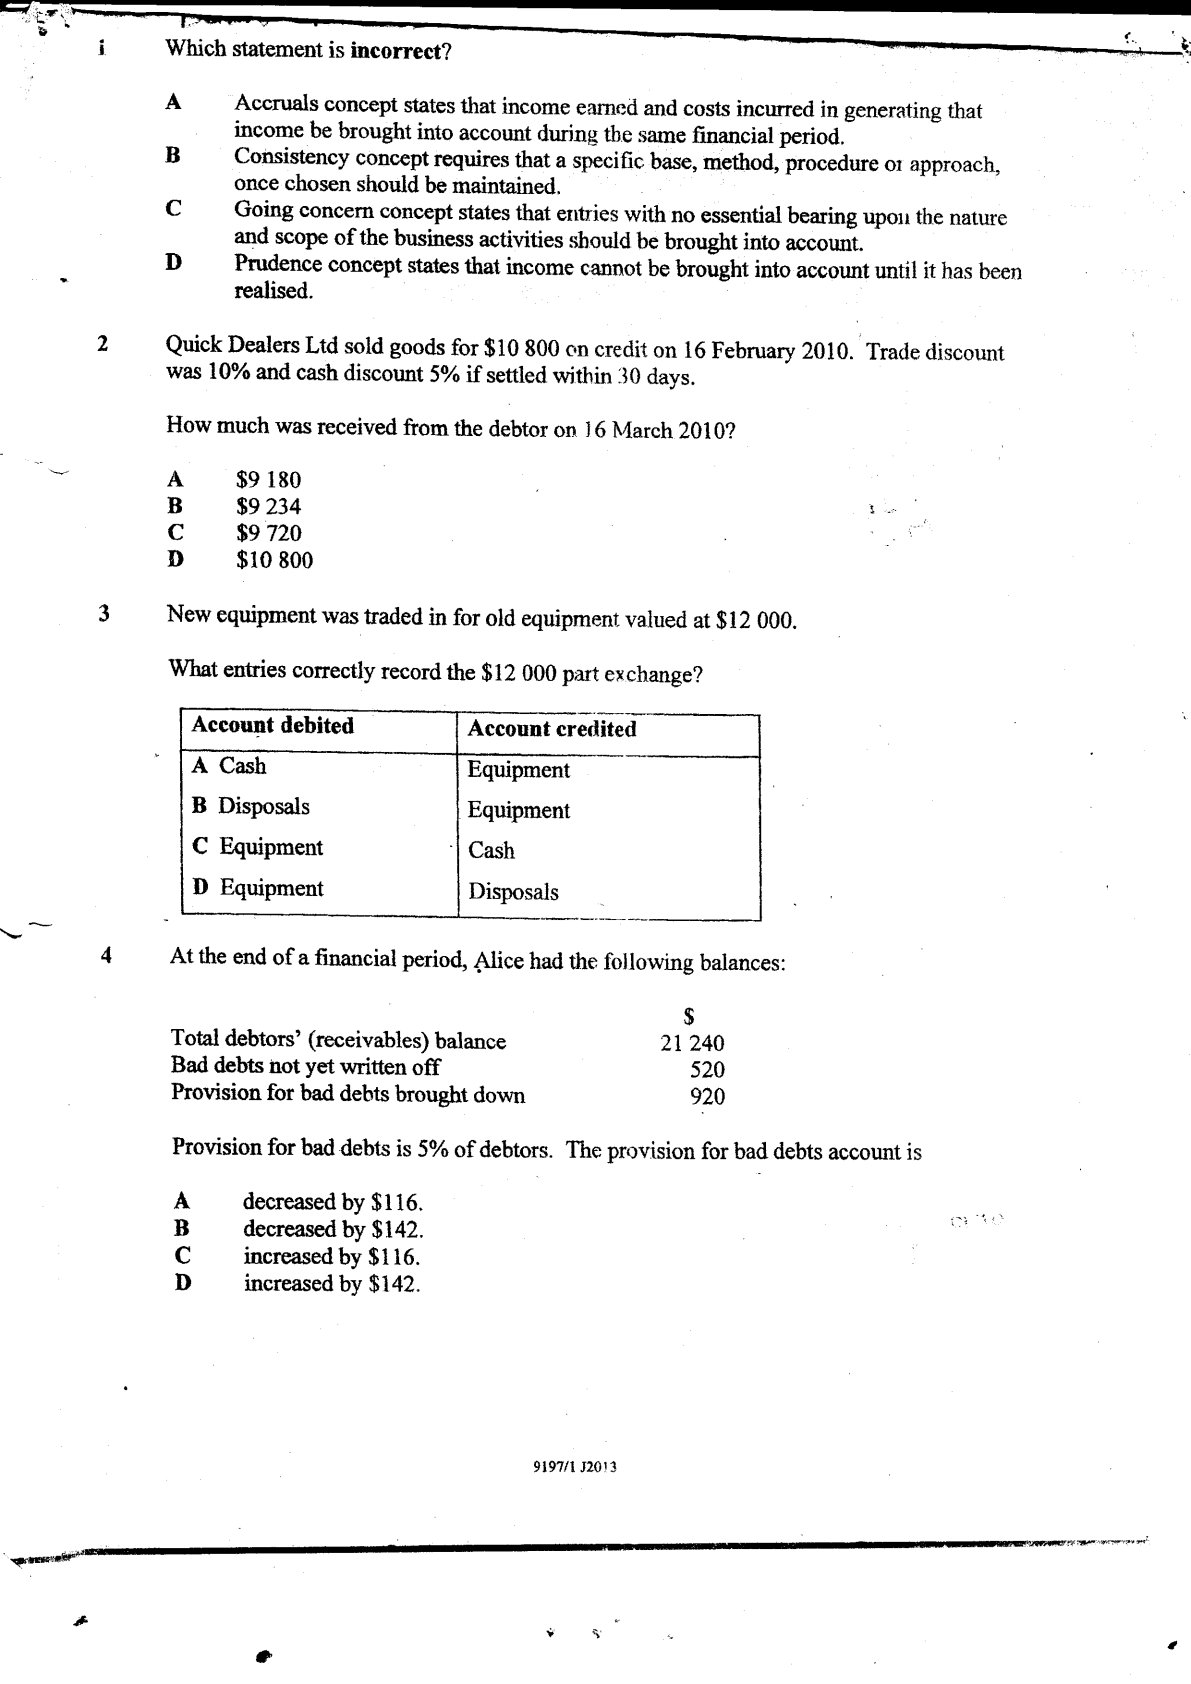
Text from the first page

i Which statement is incorrect?
A Accruals concept states that income earned and costs incurred in generating that income be brought into account during the same financial period.
B Consistency concept requires that a specific base, method, procedure or approach, once chosen should be maintained.
C Going concern concept states that entries with no essential bearing upon the nature and scope of the business activities should be brought into account.
D Prudence concept states that income cannot be brought into account until it has been realised.

2 Quick Dealers Ltd sold goods for $$ 10800$ on credit on 16 February 2010. Trade discount was $10 \%$ and cash discount $5 \%$ if settled within 30 days.

How much was received from the debtor on 16 March 2010?
A $$ 9180$
B $$ 9234$
C $$ 9720$
D $$ 10800$
3 New equipment was traded in for old equipment valued at $$ 12000$.
What entries correctly record the $$ 12000$ part exchange?

 Account debited  |  Account credited
 A Cash  |  Equipment
B Disposals  |  Equipment
C Equipment  |  Cash
D Equipment  |  Disposals

4 At the end of a financial period, Alice had the following balances:

   |  $$$
Total debtors' (receivables) balance  |  21240
Bad debts not yet written off  |  520
Provision for bad debts brought down  |  920

Provision for bad debts is $5 \%$ of debtors. The provision for bad debts account is
A decreased by $$ 116$.
B decreased by $$ 142$.
C increased by $$ 116$.
D increased by $$ 142$.

9197/1 J2013