ExamineAI
First page of ZIMSEC O-Level Principles of Accounts Paper 1 June 2000 Marking Scheme

ZIMSEC O-Level Principles of Accounts Paper 1 June 2000 Marking Scheme

Use this ZIMSEC O-Level Principles of Accounts Paper 1 June 2000 marking scheme for checking answers, revision, and exam preparation in Zimbabwe.

A free account is needed to download. Sign in or create one

Questions: ZIMSEC O-Level Principles of Accounts Paper 1 June 2000 Question Paper

Exam board
ZIMSEC
Subject
Principles of Accounts
Level
O-Level
Document
Marking Scheme
Paper
Paper 1
Paper code
7112/01
Session
June
Year
2000
File
PDF, 125 KB

About this marking scheme

This is the ZIMSEC O-Level Principles of Accounts marking scheme for Paper 1 from June 2000. It shows how marks are awarded, so you can mark your own answers to the matching question paper. The paper code is 7112/01. See the question paper.

More Principles of Accounts O-Level 2000 papers

Other years: Principles of Accounts O-Level

Text from the first page

PRINCIPLES OF ACCOUNTS
JUNE 2000

7112/01

POSSIBLE ANSWERS
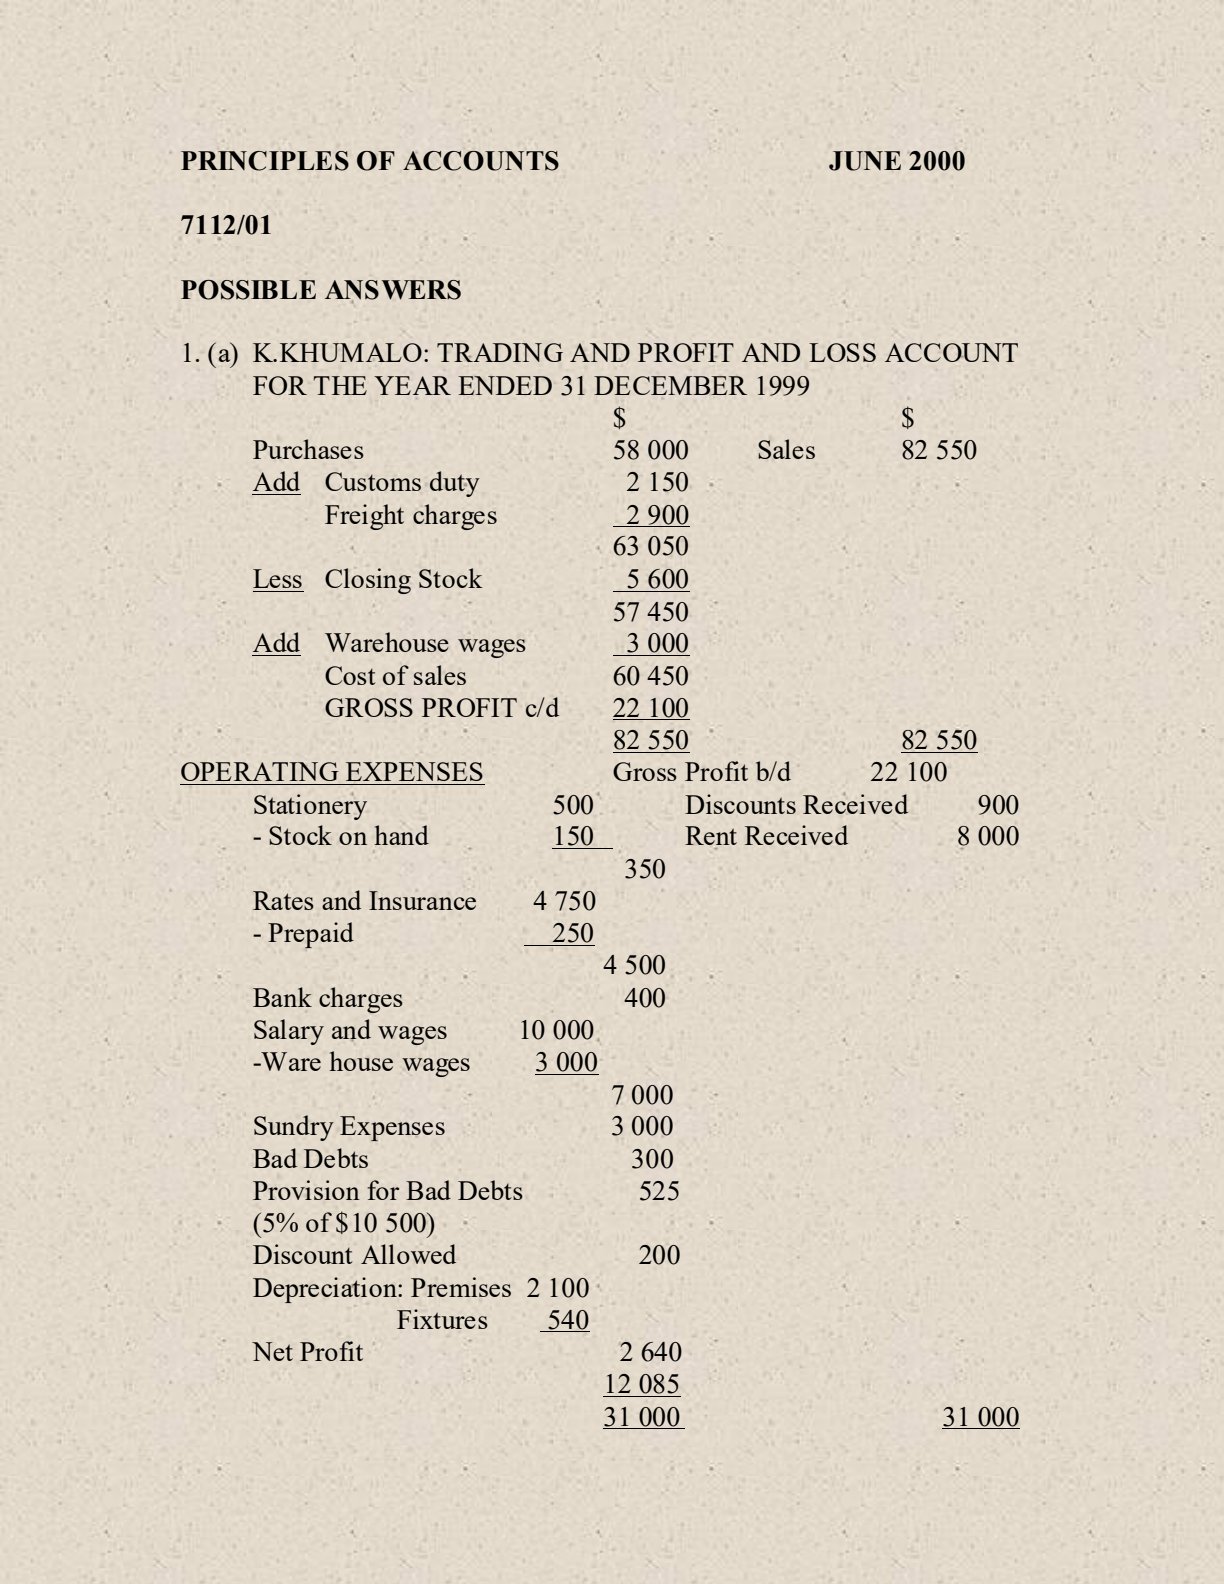
1. (a) K.KHUMALO: TRADING AND PROFIT AND LOSS ACCOUNT FOR THE YEAR ENDED 31 DECEMBER 1999

  |  $  |  & $
 Purchases  |  58000  |  Sales  |  82550
 Add Customs duty  |  2150  |  &
 Freight charges  |  2900  |  &
  |  63050  |  &
 Less Closing Stock  |  5600  |  &
  |  57450  |  &
 Add Warehouse wages  |  3000  |  &
 Cost of sales  |  60450  |  &
 GROSS PROFIT c/d  |  $\underline{22100}$  |  &
  |  $\underline{82550}$  |  & $\underline{82550}$
 OPERATING EXPENSES  |  & Gross Profit b/d  |  22100
 Stationery  |  500  |  Discounts Received  |  900
 - Stock on hand  |  150  |  Rent Received  |  8000
  |  350  |  &
 Rates and Insurance  |  4750  |  &
 - Prepaid  |  250  |  &
  |  4500  |  &
 Bank charges  |  400  |  &
 Salary and wages  |  10000  |  &
 -Ware house wages  |  $\underline{3000}$  |  &
  |  7000  |  &
 Sundry Expenses  |  3000  |  &
 Bad Debts  |  300  |  &
 Provision for Bad Debts (5\% of $10 500)  |  525  |  &
 Discount Allowed  |  200  |  &
 Depreciation: Premises 2100  |  &  |
 Fixtures $\quad \underline{540}$  |  &  |
 Net Profit  |  2640  |  &
  |  $\underline{12085}$  |  &
  |  $\underline{31000}$  |  & $\underline{31000}$