ExamineAI
First page of ZIMSEC A-Level Principles of Accounts Paper 3 November 2011 Marking Scheme

ZIMSEC A-Level Principles of Accounts Paper 3 November 2011 Marking Scheme

Use this ZIMSEC A-Level Principles of Accounts Paper 3 November 2011 marking scheme for checking answers, revision, and exam preparation in Zimbabwe.

A free account is needed to download. Sign in or create one

Exam board
ZIMSEC
Subject
Principles of Accounts
Level
A-Level
Document
Marking Scheme
Paper
Paper 3
Paper code
9197/3
Session
November
Year
2011
File
PDF, 1.6 MB

About this marking scheme

This is the ZIMSEC A-Level Principles of Accounts marking scheme for Paper 3 from November 2011. It shows how marks are awarded, so you can mark your own answers. The paper code is 9197/3.

More Principles of Accounts A-Level 2011 papers

Other years: Principles of Accounts A-Level

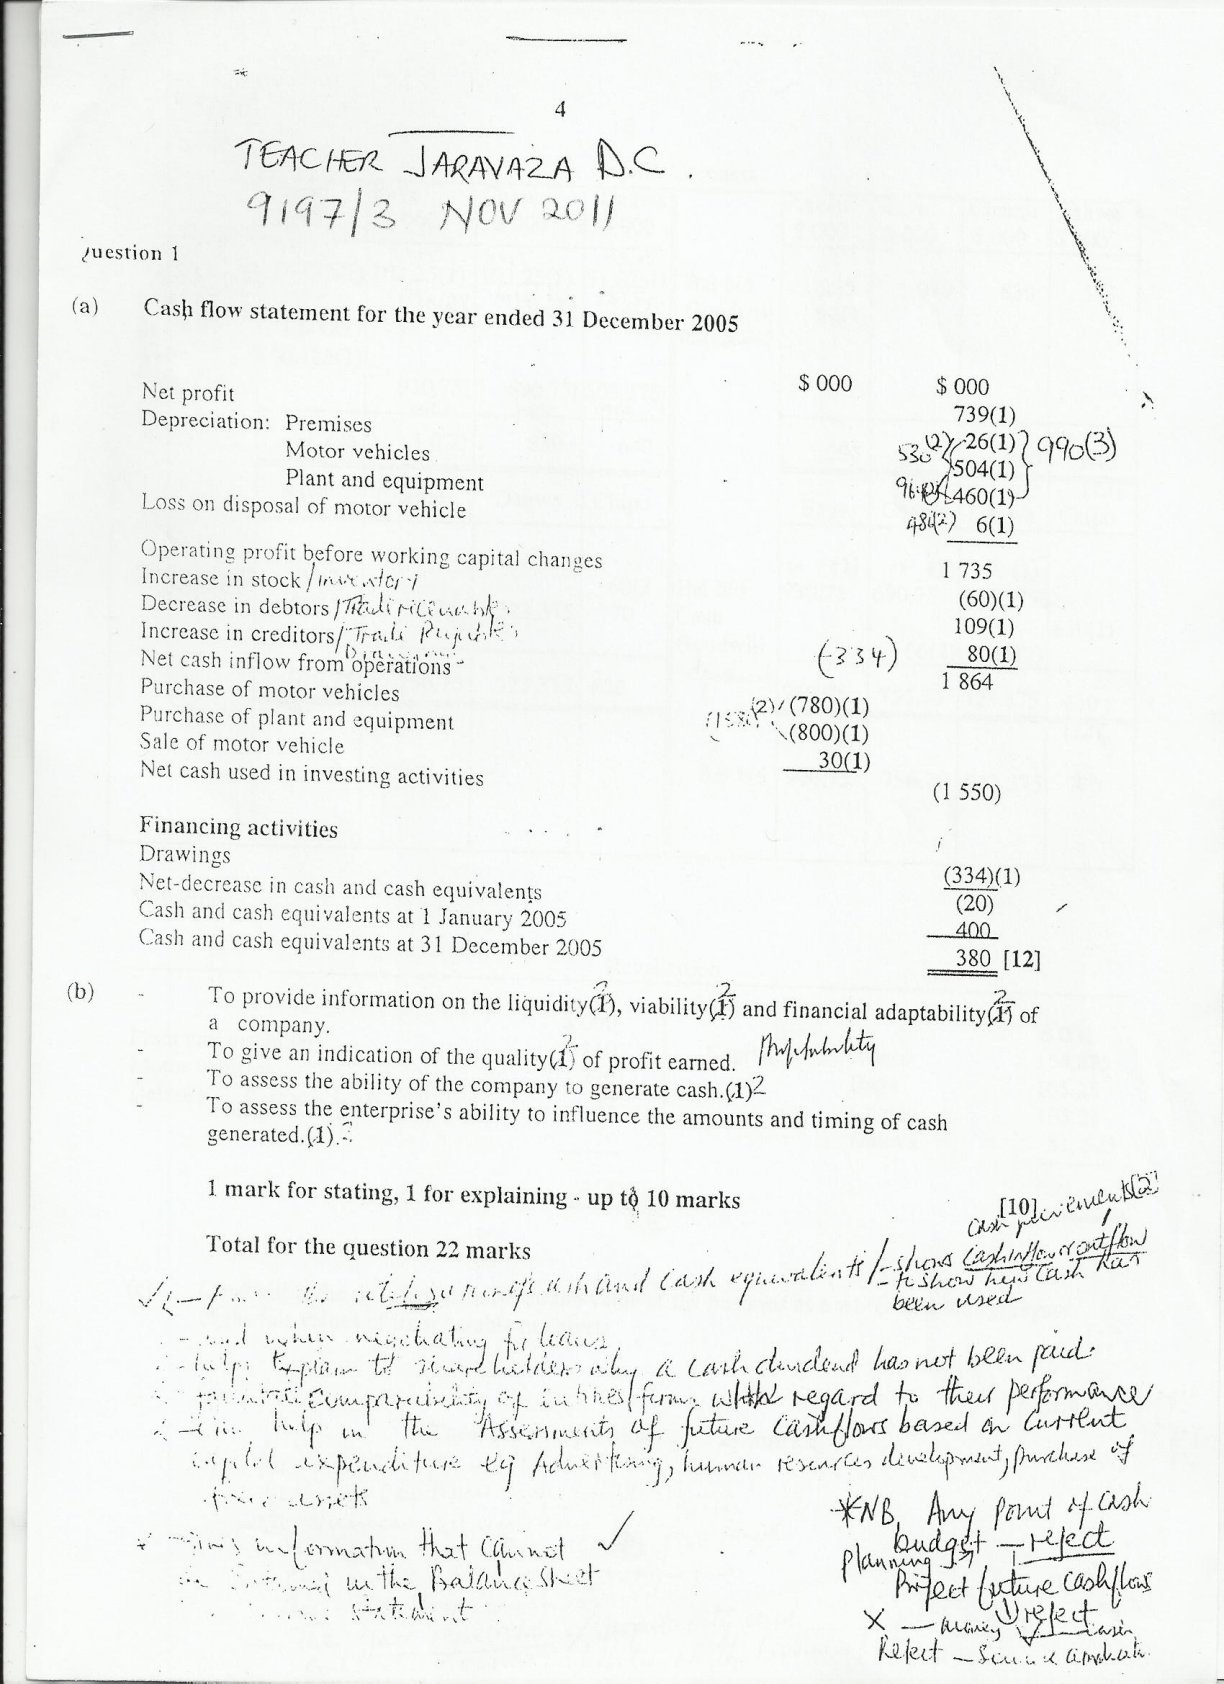
Text from the first page

4

TEACHER Jaravaza D.C. 9197/3 NOV 2011
question 1
(a) Cash flow statement for the year ended 31 December 2005

Net profit
Depreciation: Premises
Motor vehicles
Plant and equipment
Loss on disposal of motor vehicle
Operating profit before working capital changes
Increase in stock/milentory
Increase in creditors/ Trubli Pujum.
Net cash inflow from operations
Purchase of motor vehicles
Purchase of plant and equipment
Sale of motor vehicle
Net cash used in investing activities
Financing activities
Drawings
Net-decrease in cash and cash equivalents
Cash and cash equivalents at 1 January 2005
Cash and cash equivalents at 31 December 2005
\[
\begin{array}{c}
\left.$ 000 \quad \begin{array}{c}
$ 000
739(1)
\left.530^{2} y \begin{array}{c}
26(1)
504(1)
96 \times 460(1)
\end{array}\right\} 990(3)
480^{2}(2) \quad 6(1)
\end{array}\right\} .490
\end{array}
\]

1735
(60)(1)

109(1)
$\frac{80(1)}{1864}$
(1550)
(1550)
: $2^{2)}$ /(780)(1)
30(1)
$(-334) \quad \begin{array}{c}(60)(1)  109(1)  \frac{80(1)}{1864}\end{array}$
(1FB) (800)(1)
\[
\begin{array}{l}
\frac{(334)(1)}{(20)}
400
380

\end{array} \text { [12] }
\]
(b) - To provide information on the liquidity $\widehat{(1)}$, viability $\left(\frac{2}{1 \times 1}\right)$ and financial adaptability $(\widehat{\sqrt{1}})$ of a company.
- To give an indication of the quality(1) of profit earned. Phy uphulty
- To assess the ability of the company to generate cash.(1)2
- To assess the enterprise's ability to influence the amounts and timing of cash generated.(1)?

1 mark for stating, 1 for explaining - up tó 10 marks

Total for the question 22 marks been used $\therefore \rightarrow$ ii... Win in the Assemmets of future cashflows based on current
- ims intomathin that clundt $\sqrt{ }$ ∴ ....... w the fadabe sheet酼交
* NB Any pout of cish budgest - reject plannumg Prifect fucture cashflo Prifect fucture cashflows $x$ - aumy years