ExamineAI
First page of ZIMSEC O-Level Principles of Accounts Paper 3 November 2018 Question Paper

ZIMSEC O-Level Principles of Accounts Paper 3 November 2018 Question Paper

Download and practise with this ZIMSEC O-Level Principles of Accounts Paper 3 November 2018 question paper. Useful for exam revision, past paper practice, and preparation in Zimbabwe.

A free account is needed to download. Sign in or create one

Exam board
ZIMSEC
Subject
Principles of Accounts
Level
O-Level
Document
Question Paper
Paper
Paper 3
Paper code
6001/3
Session
November
Year
2018
File
PDF, 1.4 MB

About this question paper

This is the ZIMSEC O-Level Principles of Accounts question paper for Paper 3 from November 2018. Use it for exam practice under timed conditions. The paper code is 6001/3.

More Principles of Accounts O-Level 2018 papers

Other years: Principles of Accounts O-Level

Text from the first page

2

Answer all questions.
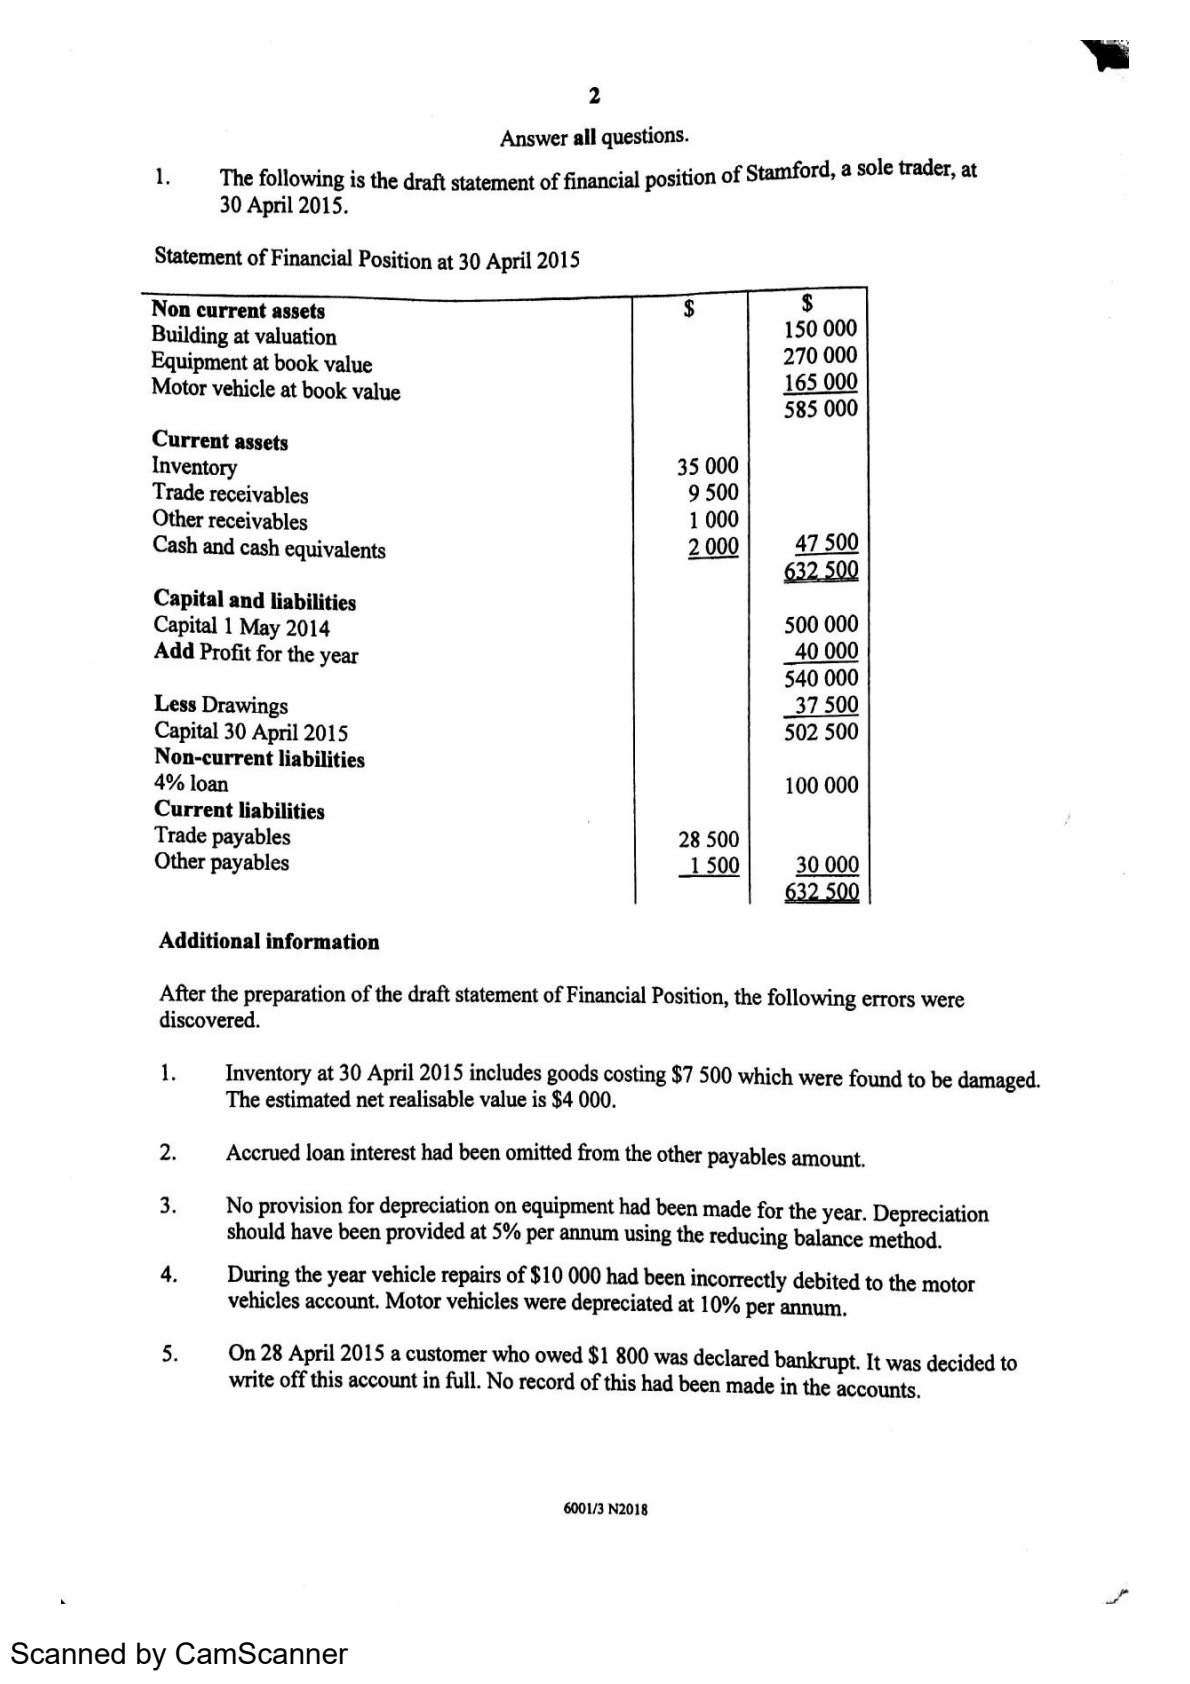
1. The following is the draft statement of financial position of Stamford, a sole trader, at 30 April 2015.

Statement of Financial Position at 30 April 2015

 Non current assets  |  $  |  $
 Building at valuation  |  & 150000
 Equipment at book value  |  & 270000
 Motor vehicle at book value  |  & $\underline{165000}$
  |  & 585000
 Current assets  |  &
 Inventory  |  35000  |
 Trade receivables  |  9500  |
 Other receivables  |  1000  |
 Cash and cash equivalents  |  $\underline{2000}$  |  $\underline{47500}$
  |  & 632500
 Capital and liabilities  |  &
 Capital 1 May 2014  |  & 500000
 Add Profit for the year  |  & 540000
 Less Drawings  |  & $\underline{37500}$
 Capital 30 April 2015  |  & 502500
 Non-current liabilities  |  &
 4\% loan  |  & 100000
 Current liabilities  |  &
 Trade payables  |  28500  |
 Other payables  |  $\underline{1500}$  |  $\underline{30000}$
  |  & 632500

Additional information
After the preparation of the draft statement of Financial Position, the following errors were discovered.
1. Inventory at 30 April 2015 includes goods costing $$ 7500$ which were found to be damaged. The estimated net realisable value is $$ 4000$.
2. Accrued loan interest had been omitted from the other payables amount.
3. No provision for depreciation on equipment had been made for the year. Depreciation should have been provided at $5 \%$ per annum using the reducing balance method.
4. During the year vehicle repairs of $$ 10000$ had been incorrectly debited to the motor vehicles account. Motor vehicles were depreciated at $10 \%$ per annum.
5. On 28 April 2015 a customer who owed $$ 1800$ was declared bankrupt. It was decided to write off this account in full. No record of this had been made in the accounts.

6001/3 N2018
Scanned by CamScanner